
What is the Daily Savings Goal Calculator?
The Daily Savings Goal Calculator divides what you still need by the days until your deadline, so a big goal becomes a small daily amount. Enter a goal, what you have saved and two dates; it gives the amount per day, week, payday and month, what a daily habit adds up to, or whether you are on track.
3,650 sounds like a lot. 10 a day does not
You want 5,000 by the end of 2027 and have 1,350 put aside. The 3,650 still to go can feel out of reach, but spread over the 365 days of the year it is 10.00 a day: about the cost of a coffee or a snack. Saving only on weekdays, it is 13.98 a weekday.
A daily amount is easier to start, and easier to check: if you miss a few days, you can see exactly how much to catch up. To see how savings earn interest each day, use the Daily Interest Calculator.
How to use the calculator
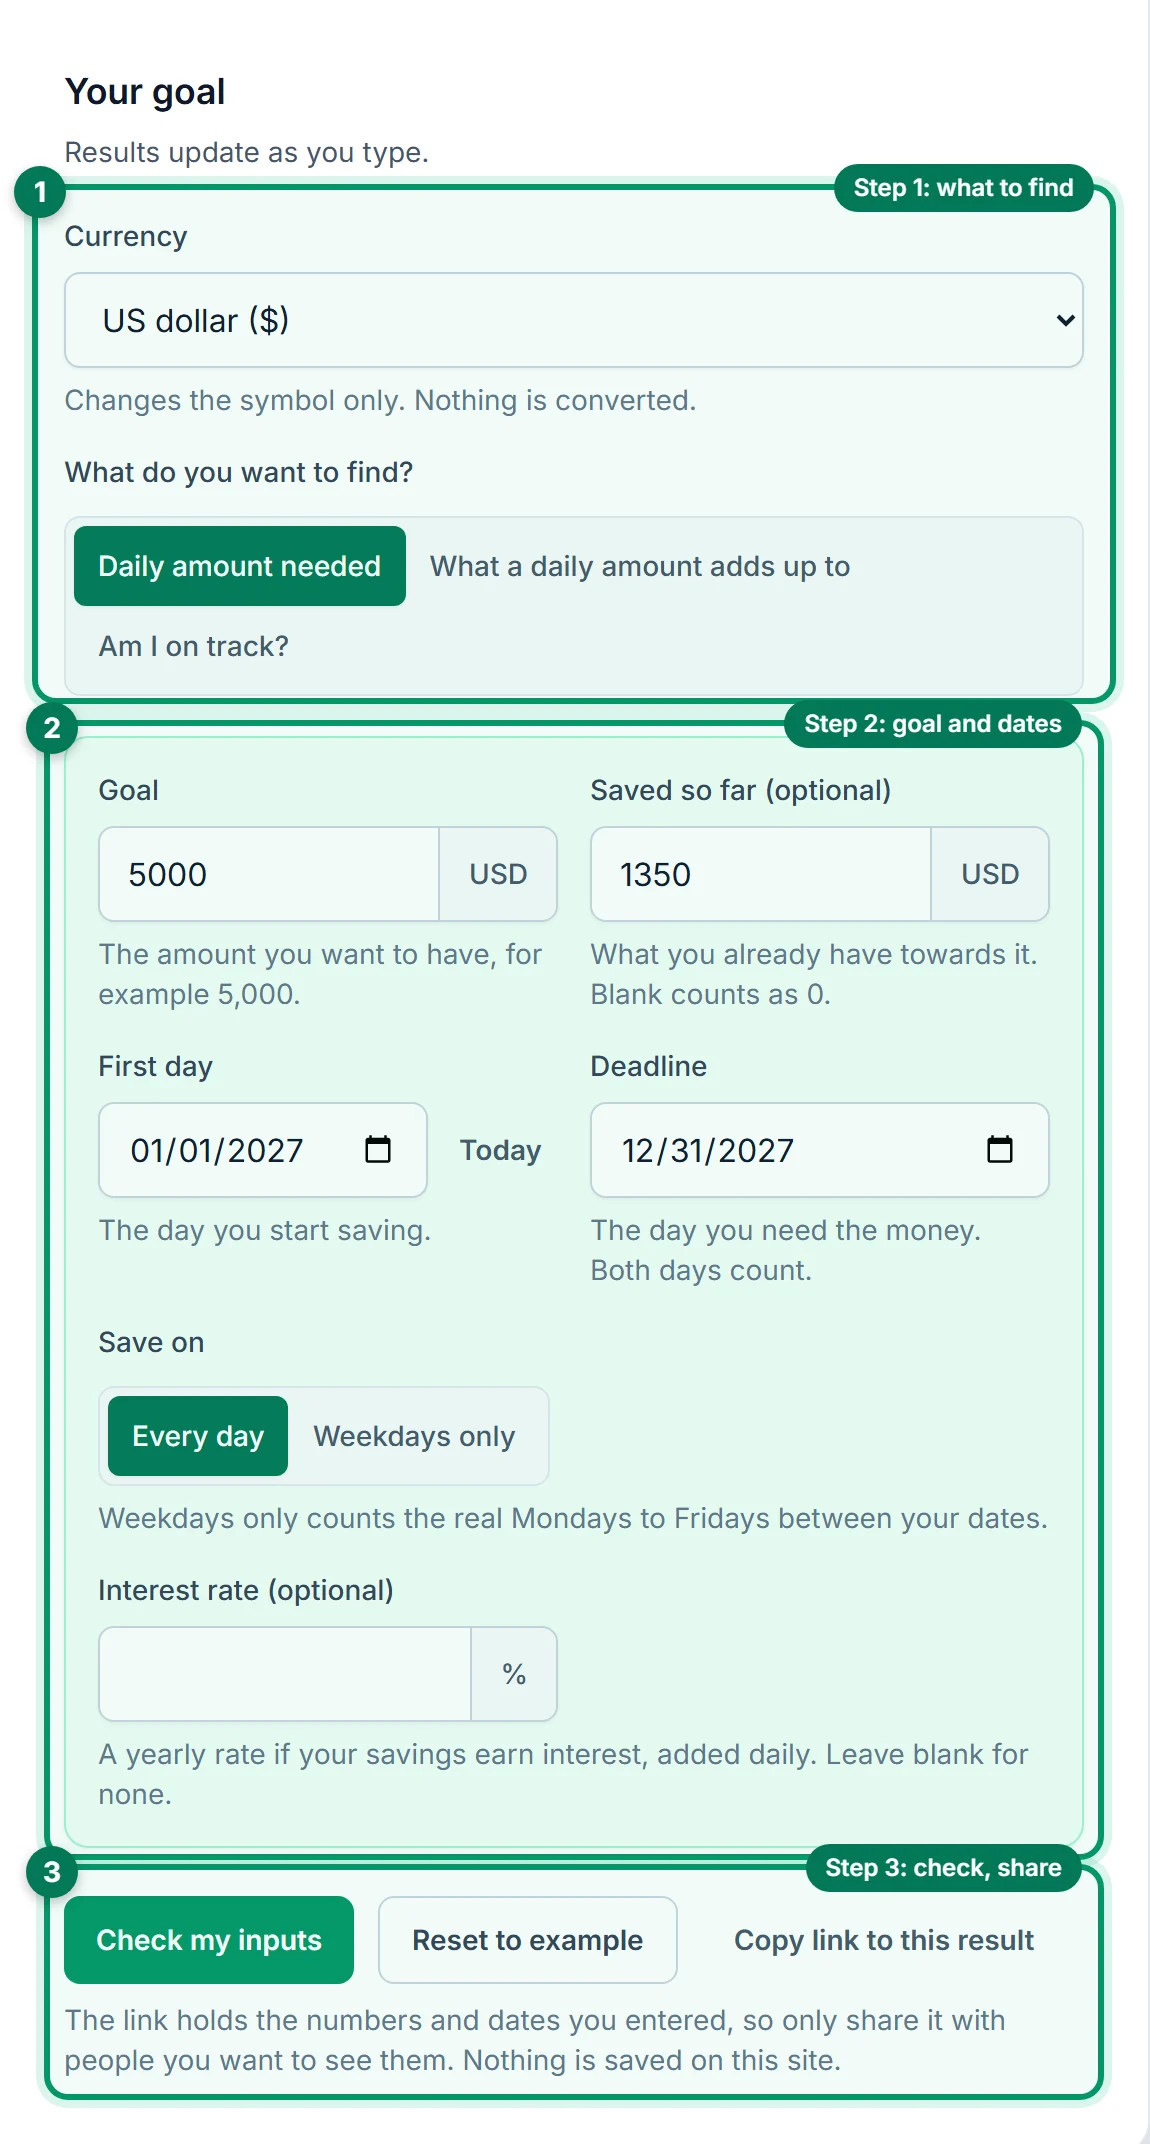
Choose what to find
Pick your Currency. Under What do you want to find?, choose Daily amount needed, What a daily amount adds up to, or Am I on track?.
Enter your goal and dates
Enter the Goal and what you have Saved so far, then the First day (press Today to start now) and the Deadline. Choose whether you Save on every day or weekdays only, and add an Interest rate if your savings earn one.
Read or share the result
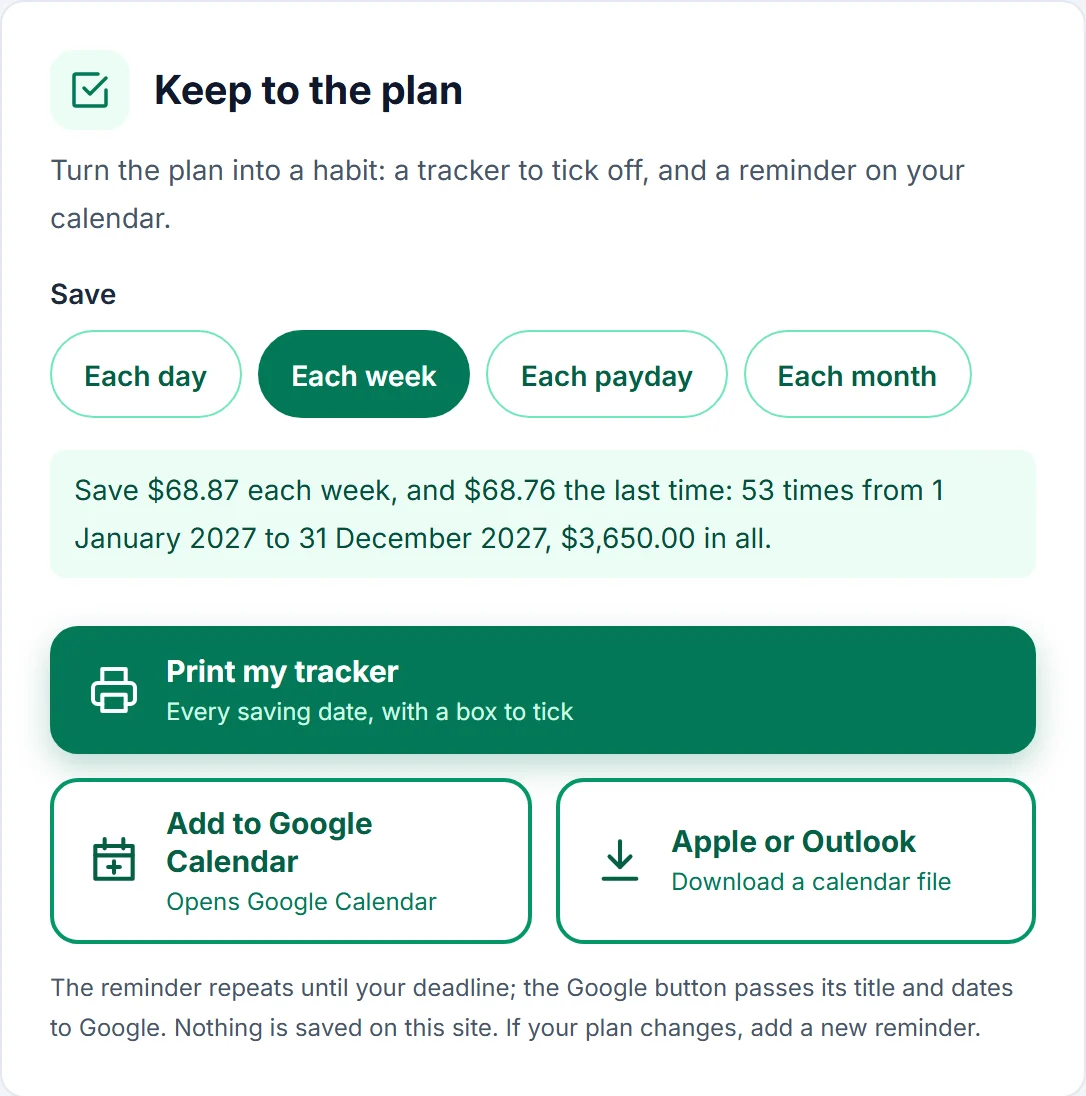
Results update as you type. Check my inputs points to anything that needs fixing, and Copy link to this result gives a link with your plan in it. Under Keep to the plan, print a tracker or add a reminder to your calendar.
Your results, explained
Here are the results for the example values: a 5,000 goal with 1,350 saved, from 1 January to 31 December 2027, saving every day. Each numbered explanation matches a highlighted area in the image.
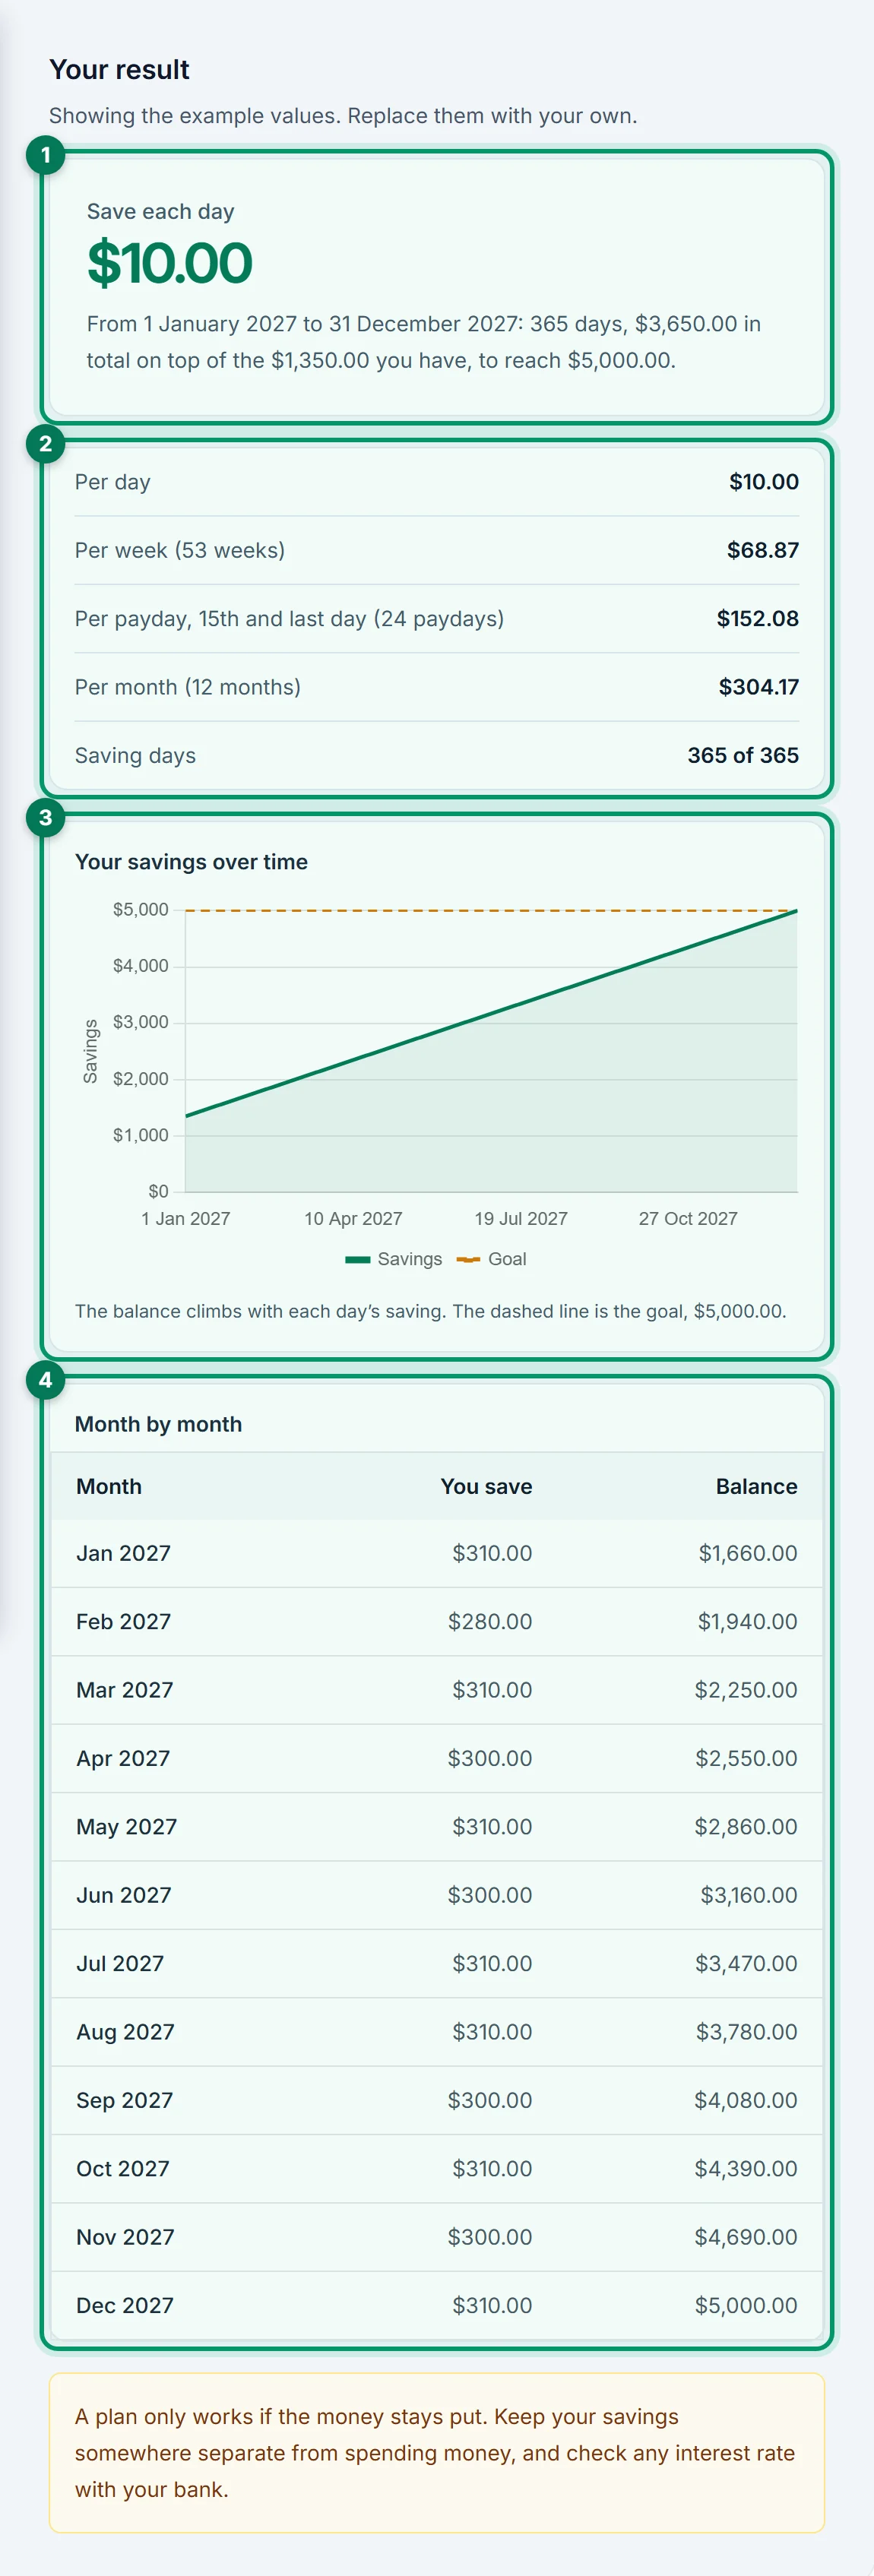
1. Save each day: 10.00
To turn the 1,350 you have into 5,000 by 31 December 2027, you need 3,650 more. Spread over the 365 days from 1 January, that is 3,650 ÷ 365 = 10.00 a day.
2. The same plan per week, payday and month
The same 3,650 spread over the real saving dates of 2027: 68.87 a week for 53 weeks from 1 January, 152.08 on each of the 24 paydays (the 15th and the last day of each month), or 304.17 a month. Pick the one that matches how you are paid.
3. The chart: your savings over time
The green line is your savings, rising from 1,350 to 5,000 through the year. The dashed line is the goal, so you can see how far you have to go at any date.
4. Month by month
Each row is one calendar month: what you save in it and the balance at its end. January has 31 days, so it adds 310.00 and ends at 1,660.00; February adds 280.00.
How each mode works: inputs and results
The calculator has three modes, chosen under What do you want to find? Pick a mode below to see exactly what it needs and what it shows. All three work with Copy link to this result.
Answers: How much do I need to save each day to reach my goal by a date?
Inputs
| Input | What to enter |
|---|---|
| Goal | The amount you want to have. Example: 5,000 |
| Saved so far (optional) | What you already have towards it. Blank counts as 0. Example: 1,350 |
| First day and Deadline | The day you start saving and the day you need the money. Both days count; Today fills in your date. Example: 2027-01-01 to 2027-12-31 |
| Save on | Every day, or weekdays only (Monday to Friday, counted from the real calendar). Example: Every day |
| Interest rate (optional) | A yearly rate if the money sits in an account that pays interest, added daily. Example: Blank |
Results
| Result | What it tells you |
|---|---|
| Save each day | The main result: the amount to put aside each saving day. The note gives the days, the total and any interest. |
| Rounded up | A whole-number daily amount and where it leaves you by the deadline. |
| Per week, Per payday, Per month | The same total spread over the real number of weeks, paydays (the 15th and the last day of each month) and months between your dates. |
| Keep to the plan | Pick how often you save to get one amount for each date, a printable tracker with boxes to tick, and a calendar reminder. |
| Chart and Month by month | Your savings over time against the goal, and each month’s saving and balance. |
The maths
Without interest: daily amount = (goal − saved so far) ÷ saving days
With interest: the balance is grown day by day, and the daily amount is solved exactly
Per week, payday or month = total to save ÷ the number of those dates between the first day and the deadline
Example
A 5,000 goal with 1,350 saved, from 1 January to 31 December 2027: 10.00 a day, or 13.98 a weekday on weekdays only.
Answers: If I save a set amount each day, how much will I have by a date?
Inputs
| Input | What to enter |
|---|---|
| Daily amount | What you put aside each saving day. Example: 10 |
| Saved so far, First day, Deadline, Save on, Interest rate | As in Daily amount needed. Example: 1,350; 2027-01-01 to 2027-12-31 |
Results
| Result | What it tells you |
|---|---|
| Saved by … | The main result: your balance on the deadline. The note splits it into what you have, what you add and any interest. |
| Per week, Per payday, Per month, Chart, Month by month and Keep to the plan | The same total in other pay cycles, how the balance builds, and the tracker and reminders. |
The maths
Without interest: total = saved so far + daily amount × saving days
With interest: each day, interest at the rate ÷ 365 is added before that day’s saving
Example
10 a day for 2027 on top of 1,350 gives 5,000.00. At 4% interest it gives 5,128.87.
Answers: Partway through, am I ahead or behind, and what must I save from now?
Inputs
| Input | What to enter |
|---|---|
| Goal | The amount you want to have. Example: 5,000 |
| Saved when you started (optional) | What you had on the day you started. Blank counts as 0. Example: 1,350 |
| Started on and Deadline | When the plan began and when you need the money. Example: 2027-01-01 to 2027-12-31 |
| Today and Saved now | Today’s date and what you have now. Example: 2027-07-01 and 3,000 |
Results
| Result | What it tells you |
|---|---|
| You’re ahead of plan by / You’re behind plan by | The main result: what you have against a steady plan from the day you started to the deadline. |
| New daily amount | What to save each day from today to still reach the goal, compared with the original amount. Keep to the plan makes a fresh tracker and reminder from today. |
The maths
Steady plan by today = saved at the start + (goal − saved at the start) × days done ÷ total days
From today: daily amount = (goal − saved now) ÷ saving days left
Example
On 1 July 2027 with 3,000 saved, a steady plan would have 3,160.00, so you are 160.00 behind. Save 10.87 a day from now instead of 10.00.
Worked example: ₱20,000 for Christmas, saving on weekdays
You want ₱20,000 by 15 December 2027 for Christmas gifts and the Noche Buena, starting from nothing on 1 January and saving only on workdays. These figures are illustrative.
Weekdays from 1 January to 15 December 2027 = 249
Per weekday = 20,000 ÷ 249 = ₱80.32, or ₱81 rounded up (₱20,169 by the deadline)
Per week (50 weeks from 1 January) = 20,000 ÷ 50 = ₱400.00
Per payday (23 paydays, the 15th and the last day of each month) = 20,000 ÷ 23 = ₱869.57
If your pay arrives on the 15th and the end of the month, setting aside ₱869.57 each payday (the last one ₱869.46) gets you there exactly, or ₱81 each workday with a little to spare.
Per day, per payday or per month: which to use
The results give one plan in four sizes. Use the one that matches how money reaches you:
- Per day suits a daily wage, tips, or a habit like skipping one purchase a day.
- Per week suits weekly pay or a weekly transfer.
- Per payday suits pay twice a month, common in the Philippines: move it to savings the day you are paid.
- Per month suits a monthly salary or an automatic monthly transfer.
Saving at the start of each pay period, before spending, is the easiest way to keep the plan: what is left is yours to spend.
How much to save per day for common goals
A quick guide with no interest, counting a month as 365 ÷ 12 days and a payday as half a month. Use the calculator for your exact dates.
| Goal | In 3 months | In 6 months | In 12 months |
|---|---|---|---|
| 10,000 | 109.59 a day1,666.67 a payday | 54.79 a day833.33 a payday | 27.40 a day416.67 a payday |
| 20,000 | 219.18 a day3,333.33 a payday | 109.59 a day1,666.67 a payday | 54.79 a day833.33 a payday |
| 50,000 | 547.95 a day8,333.33 a payday | 273.97 a day4,166.67 a payday | 136.99 a day2,083.33 a payday |
| 100,000 | 1,095.89 a day16,666.67 a payday | 547.95 a day8,333.33 a payday | 273.97 a day4,166.67 a payday |
For example, 50,000 in 6 months is 273.97 a day or 4,166.67 a payday. Already have some saved? Subtract it from the goal first, or enter it under Saved so far.
Make the habit stick
Below your inputs, Keep to the plan turns the result into something you can follow. Choose how often you save: for the example, Each week gives 68.87 on 53 dates, the last one 68.76, so the total is exactly 3,650. Print my tracker lists every date with a box to tick, and the calendar buttons add a repeating reminder until the deadline.
- Save first. Move the amount on payday, before spending, so the plan never competes with the rest of the month.
- Print the tracker. Ticking a box each time you save, like filling an alkansya, makes progress visible.
- Set a reminder. Add the plan to your calendar so the saving date comes to you.
- Check in monthly. Use Am I on track? and, if you fell behind, print a new tracker from today.
Does interest help?
A little, and more over longer plans. Saving towards 5,000 over 2027 in an account paying 4% a year needs 9.65 a day instead of 10.00, because interest supplies about 126 of the goal. Saving 10 a day at 4% gives 5,128.87.
In the Philippines, interest on bank deposits is taxed at 20%, so enter the rate after tax: a 4% account pays 3.2%. For a goal of a year or less, the habit matters far more than the rate.
Before relying on the plan
- Count the right days. If you save from your salary, use Weekdays only or the payday amount, not every day.
- Round up. A whole number is easier to keep, and the extra covers a missed day.
- Plan for surprises. Keep an emergency fund apart from goal savings, so one bill does not undo the plan.
- Check in. Use Am I on track? each month and adjust the daily amount if you fall behind.
Sources
- Department of Finance (Philippines): CMEPA and the tax on interest income Supports the flat 20% tax on interest income under CMEPA, published 17 July 2025.
Sources checked on 21 November 2026.
Frequently asked questions
How do I work out how much to save per day?
What if I only save on weekdays?
How much is that per payday?
Should I round the daily amount up?
Does interest make a difference?
I’ve fallen behind. What do I do?
Can I get a reminder to save?
Is anything saved when I copy a link to my result?
Does changing the currency convert my amounts?
Related interest and savings calculators
Keep planning with the tools that answer the next question.
- Daily Interest CalculatorSee what a balance earns or costs each day, compare two rates, or check a statement. Open calculator
- Daily Compound Interest CalculatorSee money grow with interest added every day, the days to a goal, or the daily rate needed. Open calculator
- Emergency Fund CalculatorFind how big your emergency fund should be, when you will reach it, or how long it would last. Open calculator
- 52-Week Savings Challenge CalculatorPlan the 52-week challenge, weekly or on paydays, with a printable tracker. Open calculator
- Sinking Fund CalculatorSave ahead for insurance, school fees and other planned costs, fund by fund. Open calculator
- Time to Save CalculatorSee how long a goal takes and the date you reach it, saving each day, week, payday or month. Open calculator
- APY CalculatorConvert an APR to APY for any compounding, or compare two savings accounts. Open calculator
- Simple Interest CalculatorFind simple interest, or the rate, time or principal behind it, and check add-on loans. Open calculator
- CD CalculatorSee what a certificate of deposit is worth at maturity, or what withdrawing early costs. Open calculator
- Credit Card Interest CalculatorSee how long a card takes to pay off, what paying more saves, or one month’s interest. Open calculator
- Average Daily Balance CalculatorAverage a balance over a statement period, or see what to deposit to meet a maintaining balance. Open calculator
- CAGR CalculatorFind the yearly growth rate between two values, or project one forward. Open calculator
- Dividend Reinvestment CalculatorSee how income grows when every payout is reinvested. Open calculator