
What is the Daily Compound Interest Calculator?
The Daily Compound Interest Calculator grows a balance one day at a time: each day’s interest is worked out on the balance and added to it, so tomorrow it earns interest too. Enter a starting amount, a daily or yearly rate and a length; it gives the final balance, a growth table and chart, the days to a goal, or the daily rate needed.
At a bank rate, daily compounding adds a little. At a daily rate, it adds a lot
Put 10,000 in an account paying 4% a year, compounded daily. After a year you have 10,408.08: just 8.08 more than without compounding. Now take 1,000 at 1% a day, a figure often quoted for trading or crypto. After a year it is 37,783.43, and without compounding only 4,650. The same mechanism, at a rate 91 times higher a day, turns a small extra into most of the result.
That is why this calculator shows both what compounding adds and a reality check for high daily rates. For the interest a balance earns in a single day, use the Daily Interest Calculator; to turn a bank’s APR into its APY, use the APY Calculator.
How to use the calculator
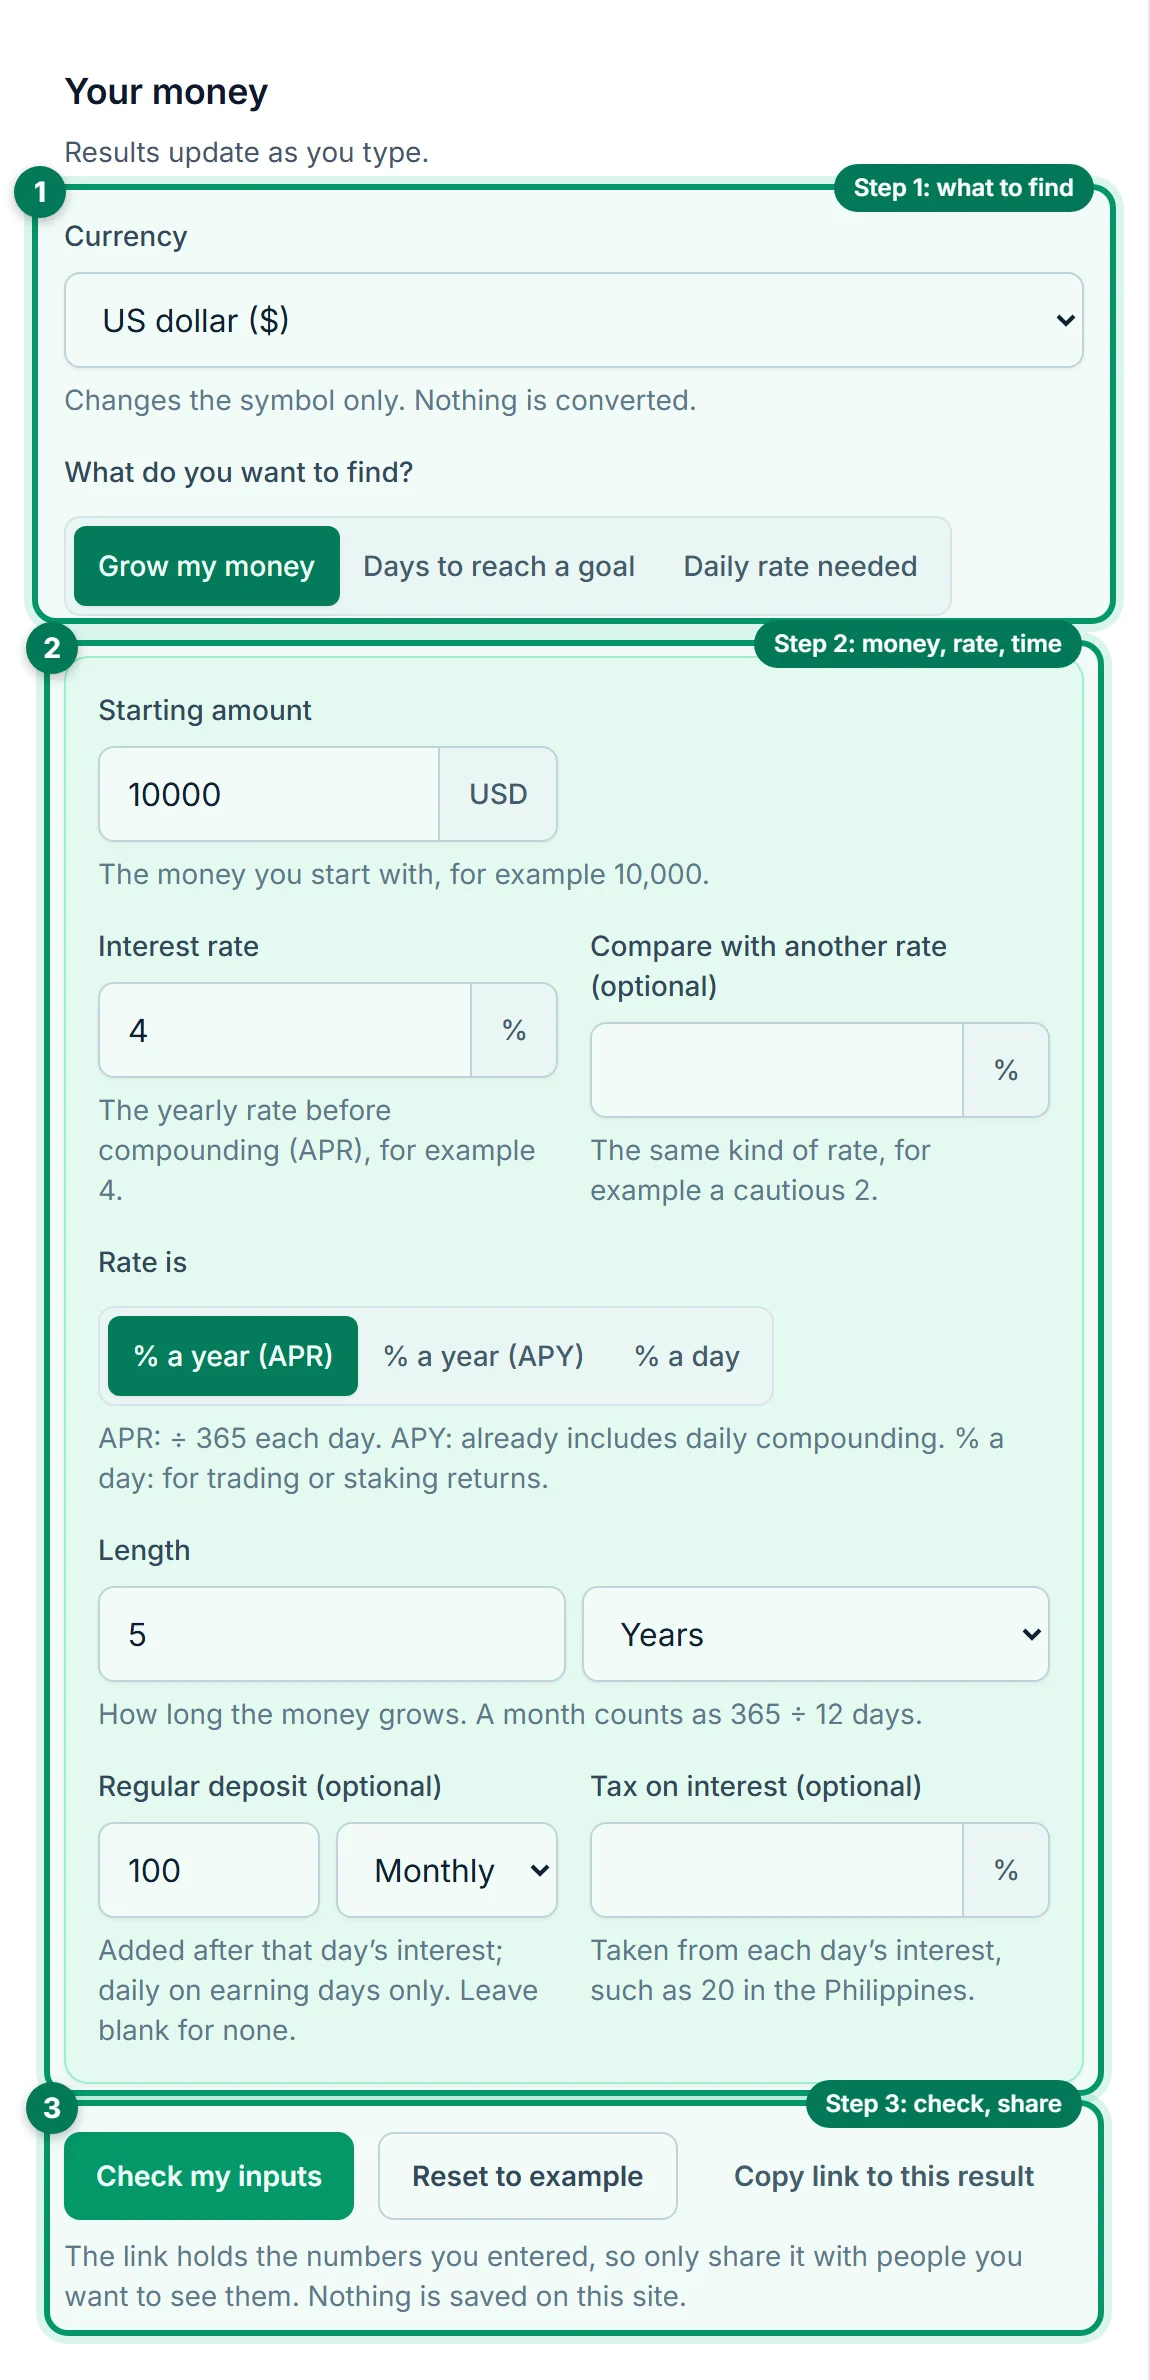
Choose what to find
Pick your Currency. Under What do you want to find?, choose Grow my money for a final balance, Days to reach a goal, or Daily rate needed.
Enter the money, the rate and the time
Enter the Starting amount, the Interest rate and whether the Rate is % a year (APR), % a year (APY) or % a day, and the Length (or the Goal). To test a cautious case, add a rate under Compare with another rate. For a daily rate, choose the Earning days. Add a Regular deposit or Tax on interest if you have them.
Read or share the result
Results update as you type. Check my inputs points to anything that needs fixing, and Copy link to this result gives a link with your numbers in it.
Your results, explained
Here are the results for the example values: 10,000 at 4% a year compounded daily, with 100 added at the end of each month for 5 years. Each numbered explanation matches a highlighted area in the image.
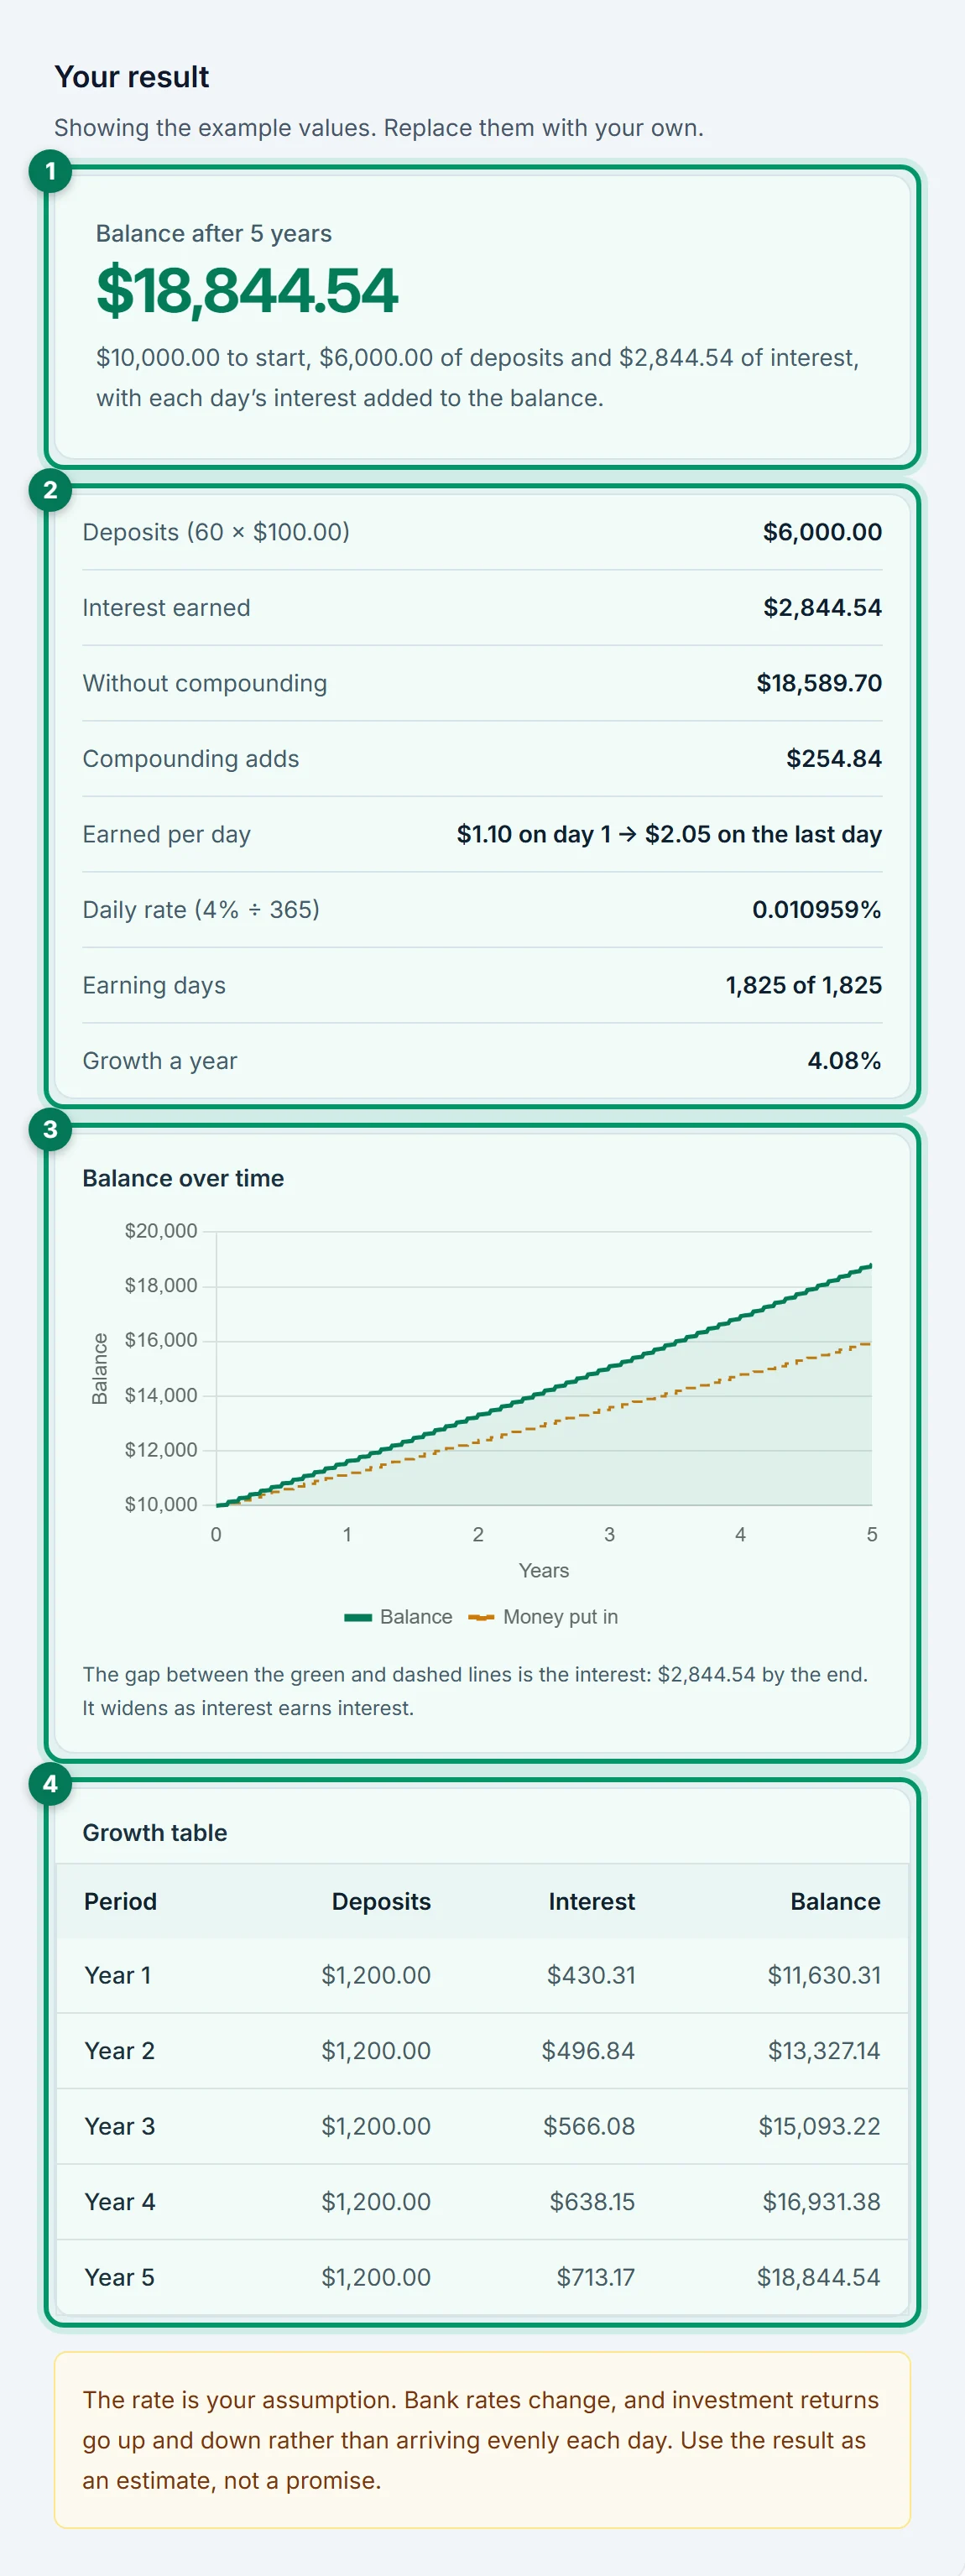
1. Balance after 5 years: 18,844.54
What 10,000 grows to at 4% a year compounded daily, with 100 added at the end of each month for 5 years. The note splits it into the 10,000 you start with, 6,000 of deposits and 2,844.54 of interest.
2. The breakdown: what compounding adds
Without compounding, the same money would reach 18,589.70, so adding each day’s interest to the balance earns 254.84 more. The daily rate is 4% ÷ 365 = 0.010959% a day, which grows money 4.08% a year. The balance earns 1.10 on the first day and 2.05 on the last.
3. The chart: balance and money put in
The green line is the balance; the dashed line is the money you put in, rising by 100 each month. The gap between them is the interest, and it widens because interest earns interest.
4. The growth table: each year
Each row gives that year’s deposits, interest and closing balance: 430.31 of interest in year 1, rising to 713.17 in year 5. Short lengths show each day, and up to 2 years each month.
How each mode works: inputs and results
The calculator has three modes, chosen under What do you want to find? Pick a mode below to see exactly what it needs and what it shows. All three work with Copy link to this result.
Answers: What will my money grow to if interest is added to it every day?
Inputs
| Input | What to enter |
|---|---|
| Starting amount | The money you start with. Example: 10,000 |
| Interest rate and Rate is | The rate, and whether it is % a year (APR), % a year (APY) or % a day. An APR is divided by 365 for each day; an APY already includes daily compounding. Example: 4, % a year (APR) |
| Compare with another rate (optional) | A second rate of the same kind, such as a cautious one or another bank’s. Example: Blank, or 2 |
| Length | How long to grow it, in days, months or years. Example: 5 years |
| Earning days | Only for a daily rate: every day, or weekdays only (5 days a week), for markets that close at weekends. Example: Every day |
| Regular deposit (optional) | An amount added Monthly, at the end of each month, or Daily, on each earning day. Example: 100, Monthly |
| Tax on interest (optional) | The share of each day’s interest taken as tax, such as 20% in the Philippines. Example: Blank |
Results
| Result | What it tells you |
|---|---|
| Balance after … | The main result: what the money grows to. The note splits it into the starting amount, deposits and interest. |
| Date | The day the length ends if you start today, worked out in your browser. |
| Breakdown | Deposits, interest, any tax, the balance without compounding and what compounding adds, the balance at the compared rate, what it earns per day, the daily rate, earning days and the yearly growth. |
| Balance over time (chart) and growth table | The balance and the money put in over time, and each day, month or year’s deposits, interest and balance. |
The maths
Daily rate = APR ÷ 365, or (1 + APY)^(1 ÷ 365) − 1, or the daily rate you enter
Each earning day: interest = balance × daily rate, less any tax, added to the balance
With no deposits: final balance = start × (1 + daily rate)^earning days
Example
10,000 at 4% a year for 5 years, with 100 each month: 18,844.54, of which 2,844.54 is interest and 254.84 comes from compounding.
Answers: How long until my balance reaches a goal at this rate?
Inputs
| Input | What to enter |
|---|---|
| Starting amount | The money you start with. Example: 10,000 |
| Interest rate and Rate is | The rate, as % a year (APR), % a year (APY) or % a day. Example: 4, % a year (APR) |
| Compare with another rate (optional) | A second rate, to see how much sooner or later it reaches the goal. Example: 2 |
| Goal | The balance you want to reach. It must be bigger than the starting amount. Example: 20,000 |
| Earning days, Regular deposit, Tax on interest | As in Grow my money. Deposits make the goal come sooner. Example: 100 each month |
Results
| Result | What it tells you |
|---|---|
| Time to reach … | The main result: the calendar days until the balance first reaches the goal, with the time in years and months and the date if you start today. |
| At … instead | With a compared rate: its days to the goal, and how many days longer or sooner that is. |
| Breakdown, chart and growth table | What the balance is made of on that day, and how it got there. |
The maths
The balance is grown day by day until it reaches the goal
With no deposits: days = log(goal ÷ start) ÷ log(1 + daily rate), rounded up
Example
10,000 at 4% a year with 100 each month reaches 20,000 in 2,040 days, about 5 years 7 months. Without the deposits it takes 6,326 days, about 17 years 4 months.
Answers: What daily rate would grow my money to a goal in a set time?
Inputs
| Input | What to enter |
|---|---|
| Starting amount | The money you start with. Example: 10,000 |
| Goal | The balance you want to reach. Example: 20,000 |
| Length | The time you have, in days, months or years. Example: 5 years |
| Earning days, Regular deposit, Tax on interest | As in Grow my money. Example: 100 each month |
Results
| Result | What it tells you |
|---|---|
| Daily rate to reach … | The main result: the rate a day that reaches the goal exactly, and the yearly growth it gives. |
| Breakdown, chart and growth table | The same figures as Grow my money, at the rate found. |
The maths
With no deposits: daily rate = (goal ÷ start)^(1 ÷ earning days) − 1
With deposits or tax, the rate is found by trying rates until the balance matches the goal
Example
Turning 10,000 into 20,000 in 5 years with 100 each month takes 0.014888% a day, 5.58% a year. Without the deposits it takes 0.037988% a day.
Worked example: 10,000 at 4% a year, compounded daily
These are illustrative figures, without the example’s monthly deposit.
Daily rate = 4% ÷ 365 = 0.010959% a day
Day 1 interest = 10,000 × 0.010959% = 1.10, so the balance is 10,001.10
After 365 days = 10,000 × (1 + 0.04 ÷ 365)^365 = 10,408.08
After 5 years (1,825 days) = 12,213.89, of which 213.89 comes from compounding
Without compounding, 4% a year on 10,000 is 400 a year, or 12,000 after 5 years. Daily compounding grows money 4.08% a year at a 4% rate, so the extra builds slowly: 8.08 in the first year, 213.89 over five.
Daily rates, trading days and the 1% a day question
Daily rates are common in trading, staking and lending apps, where a return is quoted per day. Markets that close at weekends earn only on weekdays: choose Weekdays only under Earning days, and a year has 261 earning days instead of 365.
| Rate a day | After one year | Growth a year |
|---|---|---|
| 0.1% | 1,440.25 | 44.03% |
| 1%, weekdays only | 13,423.90 | 1,242.39% |
| 1% | 37,783.43 | 3,678.34% |
Even 0.1% a day compounds to 44% a year, far above what savings or index funds have returned over long periods. Real returns arrive unevenly, with losing days, so a steady daily rate is an assumption, not a forecast. The calculator shows a reality check whenever the daily rate is 0.1% or more, with a button to compare a fifth of the rate: at 0.2% a day, the same 1,000 grows to 2,073.57 in a year, not 37,783.43.
Daily interest and the 20% tax in the Philippines
Several Philippine digital banks work out savings interest on each day’s closing balance and credit it daily, after tax. Since CMEPA, interest on deposits is taxed at a flat 20%, taken by the bank before the interest reaches you.
Enter 20 in Tax on interest to see the difference. ₱50,000 at 3.5% a year, credited daily, earns ₱1,419.73 in a year after ₱354.93 of tax. Before tax it would be ₱1,780.90. The tax also shrinks the compounding, because less interest is added to the balance each day: your money grows 2.84% a year, not 3.56%.
Before relying on the result
- A yearly rate entered as a daily one. 4% a day is not 4% a year; check Rate is.
- APR or APY. Choose the one your bank quotes under Rate is. A 4% APY earns 400 a year on 10,000; a 4% APR compounded daily earns 408.08. The APY Calculator converts between them.
- Rates that change. Promotional rates, tiers and caps change what you earn; enter the rate you expect to keep.
- Returns are not steady. Investments rise and fall. A daily rate is an average assumption, not a promise.
Before you rely on a projection:
- Confirm the rate, and whether it is a yearly or a daily rate.
- Check how often your bank or app adds interest, and on which days.
- Enter any tax taken from interest.
- Try a lower rate as well, to see a cautious result.
Sources
- Maya Bank: Maya Savings An example of daily interest: earned on the end-of-day balance at the rate ÷ 365, and credited the next day minus taxes.
- Department of Finance (Philippines): CMEPA and the tax on interest income Supports the flat 20% tax on interest income under CMEPA, published 17 July 2025.
Sources checked on 21 November 2026.
Frequently asked questions
What is daily compound interest?
Should I enter my bank’s APR or APY?
How much more does daily compounding earn than monthly?
What does 1% a day compound to?
Why do weekdays only give 261 earning days a year?
How do I include the 20% tax on interest in the Philippines?
How long does it take to double my money?
Is anything saved when I copy a link to my result?
Does changing the currency convert my amounts?
Related growth and investing calculators
Keep planning with the tools that answer the next question.
- Stock Average Down CalculatorFind your new average cost, or how many shares it takes to reach a target average. Open calculator
- Dollar-Cost Averaging CalculatorProject buying a fixed amount on a schedule and compare it with a lump sum. Open calculator
- Dividend Reinvestment CalculatorProject shares, value and income when every dividend buys more shares. Open calculator
- CAGR CalculatorTurn a start and end value into a yearly growth rate, or project one forward. Open calculator
- Stock Dividend CalculatorFind one year’s dividend income and yield from your shares. Open calculator
- Stock Profit CalculatorSee your gain or loss at today’s price. Open calculator
Related interest and savings calculators
Keep planning with the tools that answer the next question.
- Daily Interest CalculatorSee what a balance earns or costs each day, compare two rates, or check a statement. Open calculator
- Daily Savings Goal CalculatorFind how much to save each day, week or payday to reach a goal by a date. Open calculator
- Emergency Fund CalculatorFind how big your emergency fund should be, when you will reach it, or how long it would last. Open calculator
- 52-Week Savings Challenge CalculatorPlan the 52-week challenge, weekly or on paydays, with a printable tracker. Open calculator
- Sinking Fund CalculatorSave ahead for insurance, school fees and other planned costs, fund by fund. Open calculator
- Time to Save CalculatorSee how long a goal takes and the date you reach it, saving each day, week, payday or month. Open calculator
- APY CalculatorConvert an APR to APY for any compounding, or compare two savings accounts. Open calculator
- Simple Interest CalculatorFind simple interest, or the rate, time or principal behind it, and check add-on loans. Open calculator
- CD CalculatorSee what a certificate of deposit is worth at maturity, or what withdrawing early costs. Open calculator
- Credit Card Interest CalculatorSee how long a card takes to pay off, what paying more saves, or one month’s interest. Open calculator
- Average Daily Balance CalculatorAverage a balance over a statement period, or see what to deposit to meet a maintaining balance. Open calculator
- CAGR CalculatorFind the yearly growth rate between two values, or project one forward. Open calculator
- Dividend Reinvestment CalculatorSee how income grows when every payout is reinvested. Open calculator